Hi this is Team Merchant Navy Decoded !!!
Please fill the below form with your query and we will get back to you in next 12 hours.
Rest assured your data is safe with us !!!🙂
Ask Your Query| For Beginner | For Professional |
|---|---|
| GME | Engine Side |
| G.P. Rating | Deck Side |
| ETO | G.P. Rating |
| IMUCET & Sponsorship | Combo Offers |
| Free Course | MEO |
| Free Course |
| For Beginner | For Professional |
|---|---|
| GME | Engine Side |
| G.P. Rating | Deck Side |
| ETO | G.P. Rating |
| IMUCET & Sponsorship | Combo Offers |
| Free Course | MEO |
| Free Course |
Many seafarers buy a car in India after completing a good contract, clearing exams, or saving enough money from sea salary. At first, the payment may look simple: car price, insurance, registration, road tax, and dealer charges. But if the car value crosses a certain limit, one more tax item may appear on the invoice: TCS. Many seafarers confuse TCS with TDS or think it is a dealer charge. This confusion can create problems later during ITR filing.
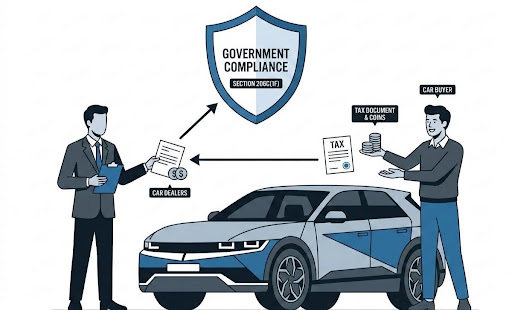
TCS means Tax Collected at Source. It is different from TDS. In TDS, tax is deducted from your income before payment reaches you. In TCS, tax is collected from you during certain specified transactions. For car purchases, the seller or dealer may collect TCS from the buyer and deposit it with the government. The Income Tax Department explains TCS as a mechanism under Section 206C where the seller collects tax from the buyer on specified transactions and deposits it with the Central Government.
TCS can apply when a seafarer buys a motor vehicle or specified luxury goods above the threshold limit. The Income Tax Department’s TCS guide mentions sale of motor vehicles or specified luxury goods of value exceeding ₹10 lakh under Section 206C(1F). It also explains that TCS is collected from a buyer paying more than ₹10 lakh for specified luxury goods, unless the buyer falls under specific excluded categories.
For a motor vehicle or specified luxury good exceeding ₹10 lakh, the standard TCS rate is 1%. The Income Tax Department’s TCS guide also shows that if PAN or Aadhaar is not furnished, the rate can be higher. For example, if a seafarer buys a car worth ₹20 lakh, 1% TCS may be around ₹20,000. This amount may appear separately on the invoice as “TCS” or “Tax Collected at Source.”
One important point is that TCS is collected on the entire sale consideration if the value of each specified luxury good exceeds ₹10 lakh. The Income Tax Department’s TCS guide explains that the ₹10 lakh limit applies per item and not on aggregate yearly sales. It also says TCS is collected at the time of receipt of payment, whether the payment is made as advance or at delivery. This is why seafarers should check the final invoice value, not only EMI or booking amount.
In a car purchase, the dealer collects TCS from the buyer and deposits it with the government. This does not mean the dealer is keeping that amount as extra profit. The dealer is acting as a collector under the tax system. For seafarers, this is important because the TCS amount should be reported against the correct PAN. If the dealer reports it correctly, it can appear in Form 26AS and may be claimed as tax credit while filing ITR.
TCS should not be treated as a permanent extra cost. It is a tax credit linked to your PAN, subject to correct collection, deposit, and reporting. When you file your ITR, this TCS can be adjusted against your final tax liability. If your final tax payable is lower than the total tax already paid or collected, refund may be possible. If your final tax payable is higher, the TCS can reduce your balance tax payable.
Yes, TCS can apply to NRI seafarers also if the car purchase transaction falls under the rule. Many seafarers assume that because they are NRI, TCS should not apply. That is not the correct way to understand it. The TCS trigger is connected with the transaction, seller, buyer, value of the motor vehicle, and applicable provisions. If a car is bought in India and the value exceeds the threshold, the dealer may collect TCS.
PAN is the key link between your car purchase and your tax record. If the dealer enters the wrong PAN, your TCS credit may not appear correctly in Form 26AS or AIS. The Income Tax Department explains that higher TDS/TCS rates apply if PAN is not quoted under Sections 206AA and 206CC. It also mentions consequences where PAN is inoperative, including higher TDS/TCS and refund-related issues. This is why seafarers should check PAN details carefully before payment.
Tax compliance history can also matter in some cases. The Income Tax Department’s TCS rate page explains that Section 206CCA provides for higher TCS if the collecte has not furnished returns for the specified assessment years, the due date has expired, and aggregate TDS/TCS is ₹50,000 or more in the relevant previous year. In such cases, tax is collected at the higher of twice the specified rate or 5%. This does not affect every seafarer automatically, but clean filing records are always safer.
Form 26AS is important because it shows tax credit details linked with your PAN. The Income Tax portal explains that Form 26AS contains details such as TDS, TCS, advance tax, self-assessment tax, refund received, specified financial transactions, demand, and refund-related information. After buying a car, seafarers should check whether the TCS collected by the dealer is properly reflected. If it is missing, the dealer may need to correct or report it properly.
AIS gives a wider view of taxpayer information. The Income Tax Department explains that from AY 2023-24 onwards, Form 26AS on TRACES mainly displays TDS and TCS-related data, while other taxpayer details are available in AIS. AIS also allows taxpayers to give feedback on reported transactions, and TIS gives aggregated information under AIS. For seafarers, checking AIS and Form 26AS together is useful before filing ITR.
Yes, seafarers may be able to claim TCS credit or refund through ITR if the TCS was correctly reported against their PAN. A refund does not come automatically just because TCS was paid. Your total income, deductions, tax payable, TDS, TCS, advance tax, and self-assessment tax are considered together in the ITR. If the total tax paid or collected is more than the final tax liability, the excess amount may be refunded after processing.
The process is simple in concept. First, the dealer collects TCS at the time of car purchase. Then the dealer deposits and reports it against your PAN. After that, the TCS should appear in Form 26AS or AIS. When you file your ITR, this TCS can be claimed as tax credit. If your final tax liability is lower than the total available tax credit, the excess may become refundable after ITR processing and verification.
Seafarers may miss TCS refund for simple reasons. Some do not check the car invoice properly. Some do not know that TCS is linked to PAN. Some do not download Form 26AS and AIS before filing ITR. Some assume that because they are NRI, the TCS amount does not matter. A ₹20 lakh car may involve around ₹20,000 TCS, and a ₹35 lakh car may involve around ₹35,000 TCS. Missing this credit can directly affect the final tax calculation.
If TCS was collected by the car dealer but is not showing in Form 26AS, do not ignore it. The Income Tax portal explains that a tax credit mismatch can happen when TDS, TCS, or challan details in the ITR do not match with Form 26AS. In this situation, seafarers should check the invoice, PAN, payment proof, and dealer details. Then contact the dealer and ask them to verify TCS deposit and reporting.
Seafarers should keep the car invoice, booking receipt, payment proof, PAN copy, dealer confirmation, Form 26AS, AIS, bank statement, and ITR working papers. The PAN on the invoice should match the PAN in the income tax records. The TCS amount on the invoice should match the TCS credit appearing in Form 26AS or AIS. If the seafarer is expecting refund, the bank account should also be validated on the income tax portal.
Before buying a car in India, first check whether the car value is above ₹10 lakh. Then ask the dealer whether TCS will apply and how much will be collected. Give the correct PAN and ensure the same PAN is recorded in the invoice and tax documents. After purchase, keep the invoice and payment proof safely. Later, check Form 26AS and AIS before filing ITR. If the credit is missing, follow up with the dealer.
Before filing ITR, seafarers should download AIS and Form 26AS and check actual TDS, TCS, and tax paid. The Income Tax portal advises taxpayers to reconcile any discrepancy with the employer, tax deductor, or bank, and to ensure details like PAN, address, contact details, and bank account details are correct in pre-filled data. For car TCS, the same principle applies: match invoice, PAN, TCS credit, AIS, Form 26AS, and bank records before filing.
The biggest mistake is treating TCS as a dealer charge or ignoring it after payment. Another mistake is giving the wrong PAN or not checking whether the PAN was entered correctly. Some seafarers also fail to check Form 26AS and AIS before filing ITR. Others assume that TCS does not matter because they are NRI. These mistakes can lead to missing tax credit, refund delay, mismatch, or unnecessary follow-up during tax season.
Seafarers should take CA help if the TCS amount is not showing in Form 26AS, PAN was entered incorrectly, the dealer is not responding, ITR refund is delayed, or there is confusion about NRI status, Indian income, or tax credit claim. CA help is also useful if the seafarer has foreign salary, NRO interest, rental income, capital gains, or multiple tax credits in the same year. Clean filing is always better than later correction.
TCS on car purchase is not something to fear, but it should not be ignored. For cars above ₹10 lakh, 1% TCS may apply under the specified motor vehicle rule. The dealer collects it from you and deposits it with the government. Later, seafarers should check whether the credit is visible in Form 26AS and AIS. The simple rule is clear: check car value, check TCS, give correct PAN, keep invoice, and claim the credit properly in ITR.
Taxation planning for seafarers should not only be considered at the end of the year while filing the return. It should include proper assessment of residential position, NRI or resident exemptions, Indian income, foreign income, NRE and NRO accounts, investments, tax credits, and major purchases. Download Sailor Pro App – Built for Seafarers, an Initiative by Merchant Navy Decoded, to stay more organised and confident in your financial planning.
TCS on car purchase for seafarers means Tax Collected at Source by the car dealer when the motor vehicle value crosses the specified threshold. The dealer collects it from the buyer and deposits it with the government.
TCS can apply when a seafarer buys a motor vehicle or specified luxury goods exceeding ₹10 lakh. The TCS is generally collected by the dealer at the time of payment.
The standard TCS rate on motor vehicles or specified luxury goods exceeding ₹10 lakh is 1%. If PAN or Aadhaar is not furnished, a higher rate may apply.
No, TCS is not a permanent extra tax. It is a tax credit linked to PAN. It can be adjusted against final tax liability while filing ITR, subject to correct reporting.
Yes, NRI seafarers may also face TCS if they buy a car in India and the transaction falls under the applicable TCS rule. Residential status alone does not automatically remove the transaction-based TCS trigger.
Yes, seafarers may claim TCS credit in ITR. If total tax paid or collected is more than final tax liability, the excess amount may be refunded after ITR processing and verification.
Seafarers can check car purchase TCS in Form 26AS and AIS. They should also match it with the car invoice, payment proof, PAN details, and bank records before filing ITR.
If TCS is not showing in Form 26AS, check whether the PAN on the invoice is correct. Then contact the dealer and ask them to verify TCS deposit and reporting.
PAN is important because TCS credit is reported against PAN. If the PAN is wrong, invalid, or not furnished, credit may not appear correctly and a higher TCS rate may apply.
Seafarers should take CA help if the TCS credit is missing, PAN is wrong, refund is delayed, or there is confusion about ITR filing, NRI status, Indian income, or tax credit claim.
Disclaimer :- The opinions expressed in this article belong solely to the author and may not necessarily reflect those of Merchant Navy Decoded. We cannot guarantee the accuracy of the information provided and disclaim any responsibility for it. Data and visuals used are sourced from publicly available information and may not be authenticated by any regulatory body. Reviews and comments appearing on our blogs represent the opinions of individuals and do not necessarily reflect the views of Merchant Navy Decoded. We are not responsible for any loss or damage resulting from reliance on these reviews or comments.
Reproduction, copying, sharing, or use of the article or images in any form is strictly prohibited without prior permission from both the author and Merchant Navy Decoded.
Decoded Discount Alert! up to 50% OFF
Use Coupon Code Deep50